You have worked in public service for ten years or more, but your PSLF count is stuck short of 120. Maybe you spent months in forbearance during a job change, a hardship, or the long SAVE forbearance. In 2026, one of the most searched PSLF questions is whether those lost months can be recovered. For many borrowers the answer is PSLF Buyback. Here is who qualifies, how the price is set, how long requests are taking, and what can go wrong.
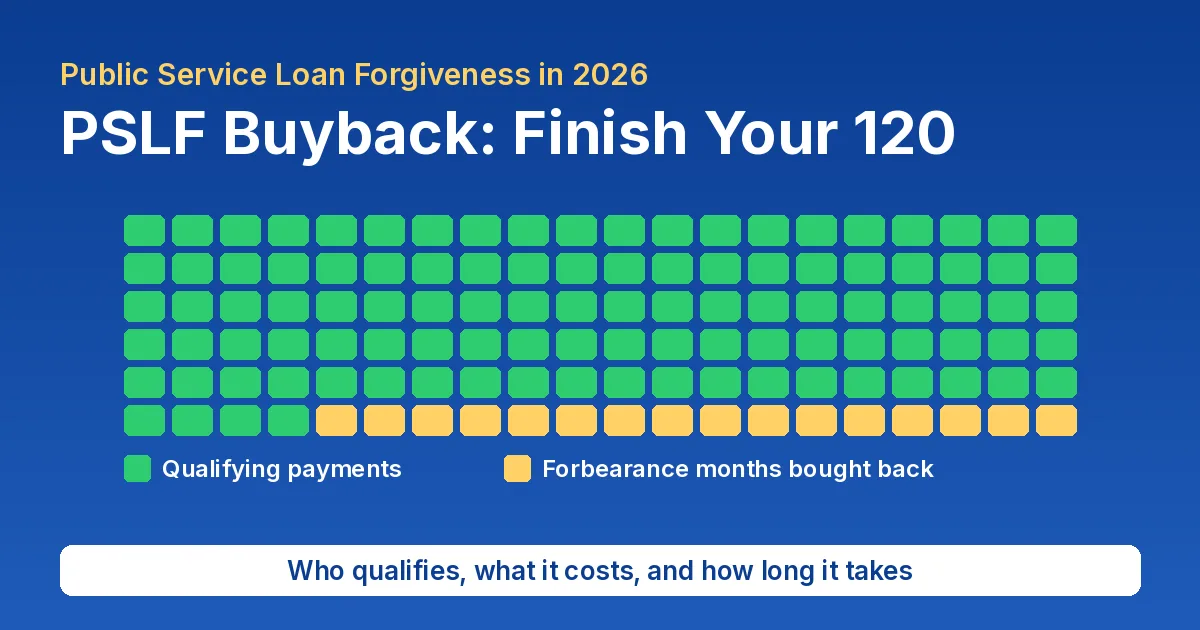
PSLF Buyback lets you pay for past months spent in deferment or forbearance so they count toward the 120 payments PSLF requires. It only works if you already have at least 120 months of certified qualifying employment and the bought-back months would finish your count. The price is roughly what your income-driven payment would have been at the time. Once an offer arrives, the full amount is due within 90 days. Requests are taking close to a year in 2026, so getting the details right the first time matters.
All of these need to be true:
Millions of borrowers spent 2024 and 2025 in the SAVE forbearance while the plan was tied up in court. A court order ended SAVE in March 2026, and borrowers have been moved to other plans. Federal Student Aid confirms that time in the SAVE forbearance does not count toward PSLF, but it can be bought back once you have 120 months of qualifying employment.
If you are still short of 120 months of employment, buyback is not open to you yet. The faster path is getting onto a plan that counts for PSLF now, such as IBR, PAYE, ICR, or the new Repayment Assistance Plan (RAP). Payments on the Tiered Standard Plan do not count. Our guide to choosing a plan after SAVE compares the options.
The buyback price is what your payment likely would have been on an income-driven plan during the months being bought back. It is based on your income and family size back then, not your income today.
For borrowers with low income during those years, the price can be small. For others it can be several thousand dollars. Either way, it is usually far less than the balance that would be forgiven, and PSLF forgiveness is not taxed as income by the federal government.
Regular monthly payments should keep going while a request is pending. Stopping them can create new non-qualifying months or a past-due account.
The only public numbers come from status reports the Department filed in a federal lawsuit brought by the American Federation of Teachers. According to the May 2026 report:
Since then, the Department told reporters in October 2026 that about 82,000 requests were pending and that it decided about 2,500 in August. It does not publish a processing time, so a wait of close to a year is common. A second request does not move you up the line. It only adds a duplicate.
In October 2025 the Department finalized a rule that would have let it remove some employers from PSLF. Federal courts in Massachusetts and Washington, D.C., vacated that rule on June 30, 2026, one day before it was set to take effect, and the Department dropped its appeals on October 21 and 22, 2026. No employer was disqualified under it. Government agencies at every level and 501(c)(3) nonprofits still qualify, and full-time work for some other nonprofits that provide qualifying public services can also count.
If a buyback or PSLF request was denied, it is often worth a second look, because many denials turn on paperwork, not eligibility.
You tell us about your jobs and your loans once. We do the work:
PSLF Buyback help is part of our $495 flat-fee PSLF service. Before we change anything, we check how it affects your other options, including Borrower Defense. You can see all of our loan help services in one place.
Related reading: our full PSLF guide, Teacher Loan Forgiveness vs. PSLF, and forgiveness for military, firefighters, and police. If your loans are in default, they need to be brought current before PSLF payments can count. Legal Touch handles default resolution by consolidation for $495 if you are eligible. If that does not fit, the Department of Education's Default Resolution Group can be reached at 1-800-621-3115.
PSLF Buyback lets a borrower pay for certain past months spent in deferment or forbearance so those months count as qualifying PSLF payments. It is meant for people who worked for a qualifying employer the whole time but were not making qualifying payments during some of those months.
You need Direct Loans with a balance still owed, at least 120 months of certified qualifying employment, and deferment or forbearance months on or after October 1, 2007, that line up with that employment. The buyback must bring you to 120 qualifying payments, which means it is a final step toward forgiveness, not a way to add a few months along the way.
Yes, if you meet the other rules. Federal Student Aid says the SAVE forbearance months do not count toward PSLF on their own, but they are among the months that can be bought back once you have 120 months of qualifying employment.
The price is based on what you likely would have paid on an income-driven plan during those months, using your income and family size from that time, not today. If you were on an income-driven plan right before or after a short forbearance, the lower of those payments is usually used. If not, tax records for those years are needed.
Often close to a year. The Department reported about 88,000 pending requests at the end of April 2026, including 18,000 to 19,000 duplicates, and later told reporters about 82,000 were pending. It does not publish a processing time.
The buyback agreement becomes void, and a new request is needed, which goes to the back of the line. That is why the payment window is one of the most important dates in the process.
Most likely, if it is a government agency or a 501(c)(3) nonprofit. The 2025 rule that would have let the Department disqualify some employers was vacated by federal courts on June 30, 2026, before it took effect, and the Department dropped its appeals in October 2026.
No. Only the U.S. Department of Education decides buyback requests and PSLF forgiveness. Legal Touch is not a law firm and makes no guarantees. We make sure your request is complete, your employment is certified, and no deadline is missed.
Find out how many months you may be able to buy back and whether it likely gets you to 120. Check My Eligibility or call 800-261-2946.
Questions first? Contact our team.
Sources: Federal Student Aid, PSLF Buyback and SAVE Plan borrowers FAQ; MOHELA PSLF information; U.S. Department of Education status report in AFT v. Department of Education, filed May 19, 2026; NASFAA; Inside Higher Ed, October 22, 2026; Associated Press.
Legal Touch is not a law firm and does not give legal advice. Results are not guaranteed. Only the U.S. Department of Education decides PSLF and buyback requests, and Legal Touch is not affiliated with it or any government agency. You can request PSLF Buyback yourself, for free, at StudentAid.gov. We will never ask for your StudentAid.gov username or password.
Attorney-formed document preparation for Title IV federal student loan program applications. Not a law firm.


Sales Key LLC dba Legal Touch Borrower Defense · (800) 261-2946 · Copyright . All rights reserved. Designed by Explore Logics
Sales Key LLC dba Legal Touch Borrower Defense, 641 E San Ysidro Blvd Num B3328, San Ysidro, CA 92173