If you serve in the military, fight fires, or work in law enforcement, there are real federal programs that can lower or erase your student loans. The problem is that each one has its own rules, and picking the wrong loan type or repayment plan can quietly cost you years of credit. Here is what exists in 2026, who likely qualifies, and how Legal Touch handles the paperwork for you.
For most service members, firefighters, and police officers, the biggest program is Public Service Loan Forgiveness (PSLF), which can forgive the remaining balance on Direct Loans after 120 qualifying payments. Older Perkins Loans have their own cancellation for firefighters, officers, and some military service. Service members also get special interest benefits, and veterans with a qualifying VA disability rating likely qualify for a disability discharge. Many people qualify for more than one.
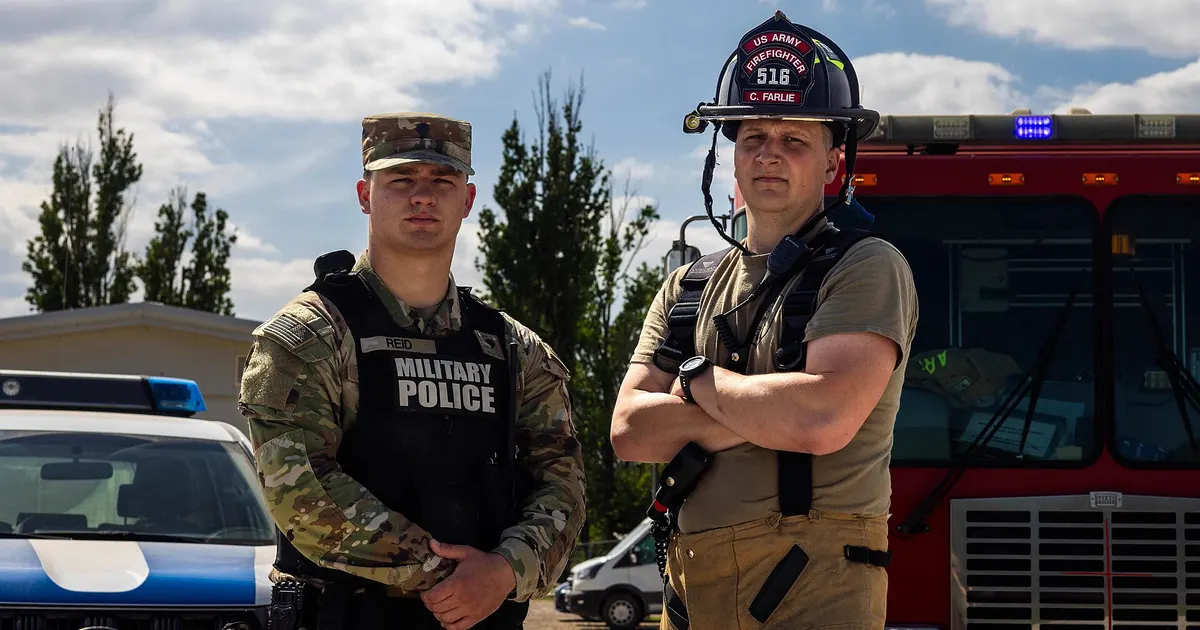
PSLF is open to anyone who works full-time for a qualifying employer. Government employers qualify, which covers the U.S. Armed Forces, federal agencies, and state, county, city, and tribal fire and police departments. Many nonprofit fire and EMS organizations also qualify.
2026 note: The SAVE plan has ended, and borrowers who were in it are being told to choose a new plan. Choosing a plan that does not count for PSLF can stall your progress. Learn more on our PSLF help page.
If you still have a Federal Perkins Loan, you may not need PSLF for it at all. Perkins cancellation can erase up to 100% of the loan over five years of full-time service as:
Each year of qualifying service must be 12 consecutive months. The school or servicer cancels 15% of the original balance for each of years one and two, 20% for years three and four, and 30% for year five, plus the interest that built up during each year. Administrative and support roles generally do not qualify. One warning: if a Perkins Loan is consolidated, the Perkins cancellation option is gone for good.
Veterans the VA rates as 100% disabled from a service-connected condition, or totally disabled based on individual unemployability, likely qualify for a Total and Permanent Disability (TPD) discharge. The Department of Education matches records with the VA and sends a letter to borrowers it identifies, but letters can be delayed or missed. Firefighters and officers who were seriously injured on the job may also qualify through a Social Security disability determination or a doctor. See our guide to SSDI and TPD discharge.
| Program | Who it helps | What it does | Main catch |
|---|---|---|---|
| PSLF | Military, firefighters, police, and other public employees | Forgives the rest of your Direct Loans after 120 qualifying payments | Needs the right loans, the right plan, and certified employment |
| Perkins cancellation | Firefighters, sworn officers, and military in hostile areas | Cancels up to 100% of Perkins Loans over 5 years | Lost if the Perkins Loan is consolidated |
| 0% hostile area interest | Service members receiving hostile fire or imminent danger pay | Stops interest for up to 60 months | Direct Loans disbursed on or after Oct. 1, 2008 only |
| SCRA 6% cap | Service members with loans from before active duty | Caps interest at 6% during service | Does not reduce the balance |
| TPD discharge | Veterans with a qualifying VA rating and others with a lasting disability | Cancels eligible federal loans | Needs a qualifying VA, Social Security, or doctor determination |
For more on how military and federal service count, see our older guide to military and federal employee loan forgiveness.
You tell us about your service and your loans. We do the work:
Each service is a $495 flat fee. See all of our Loan Help Services, our guide to Teacher Loan Forgiveness vs. PSLF, and our help for borrowers in student loan default or deciding between rehabilitation and consolidation.
Usually, yes. Full-time employees of a city, county, state, tribal, or federal fire department or police agency work for a government employer, which is a qualifying employer for Public Service Loan Forgiveness. Full-time generally means at least 30 hours a week. You still need eligible Direct Loans, a qualifying repayment plan, and 120 qualifying payments.
Yes. Active duty service and full-time National Guard duty count as qualifying public service. Weekend drills alone usually do not count as full-time employment. Months in a military service deferment can often count toward PSLF too, with some limits for borrowers enrolled in the new Repayment Assistance Plan.
Yes. Federal Perkins Loans can be canceled for full-time service as a firefighter, a sworn law enforcement or corrections officer, or for active duty in an area of hostilities that qualifies for special pay. Cancellation is 15% for each of the first two years, 20% for years three and four, and 30% for year five, up to 100%.
Not without checking first. Consolidating a Perkins Loan into a Direct Consolidation Loan makes it eligible for PSLF, but it permanently gives up Perkins cancellation. If you work as a firefighter or officer, Perkins cancellation may wipe out that loan in five years, so the order matters.
The new Repayment Assistance Plan (RAP) became available on July 1, 2026, and it counts toward PSLF. The SAVE plan ended, and borrowers who were in SAVE must pick a new plan. For loans first made on or after July 1, 2026, only RAP payments count toward PSLF. PAYE and ICR payments count only through June 30, 2028.
Many do not. Veterans the VA rates as 100% disabled from a service-connected condition, or totally disabled based on individual unemployability, likely qualify for a Total and Permanent Disability discharge. The Department of Education matches records with the VA and sends a notice to borrowers it identifies.
No. Your loan holder and the U.S. Department of Education make every decision. Legal Touch is not a law firm and makes no guarantees.
Find out in one call which programs likely fit your service. Check My Eligibility or call 800-261-2946.
Questions first? Contact our team.
Legal Touch is not a law firm and does not give legal advice. Results are not guaranteed. Every decision is made by your loan holder or the U.S. Department of Education. Legal Touch is not affiliated with the U.S. military, the Department of Defense, or the VA. You can apply for these programs yourself for free through your loan servicer or StudentAid.gov.
Attorney-formed document preparation for Title IV federal student loan program applications. Not a law firm.


Sales Key LLC dba Legal Touch Borrower Defense · (800) 261-2946 · Copyright . All rights reserved. Designed by Explore Logics
Sales Key LLC dba Legal Touch Borrower Defense, 641 E San Ysidro Blvd Num B3328, San Ysidro, CA 92173